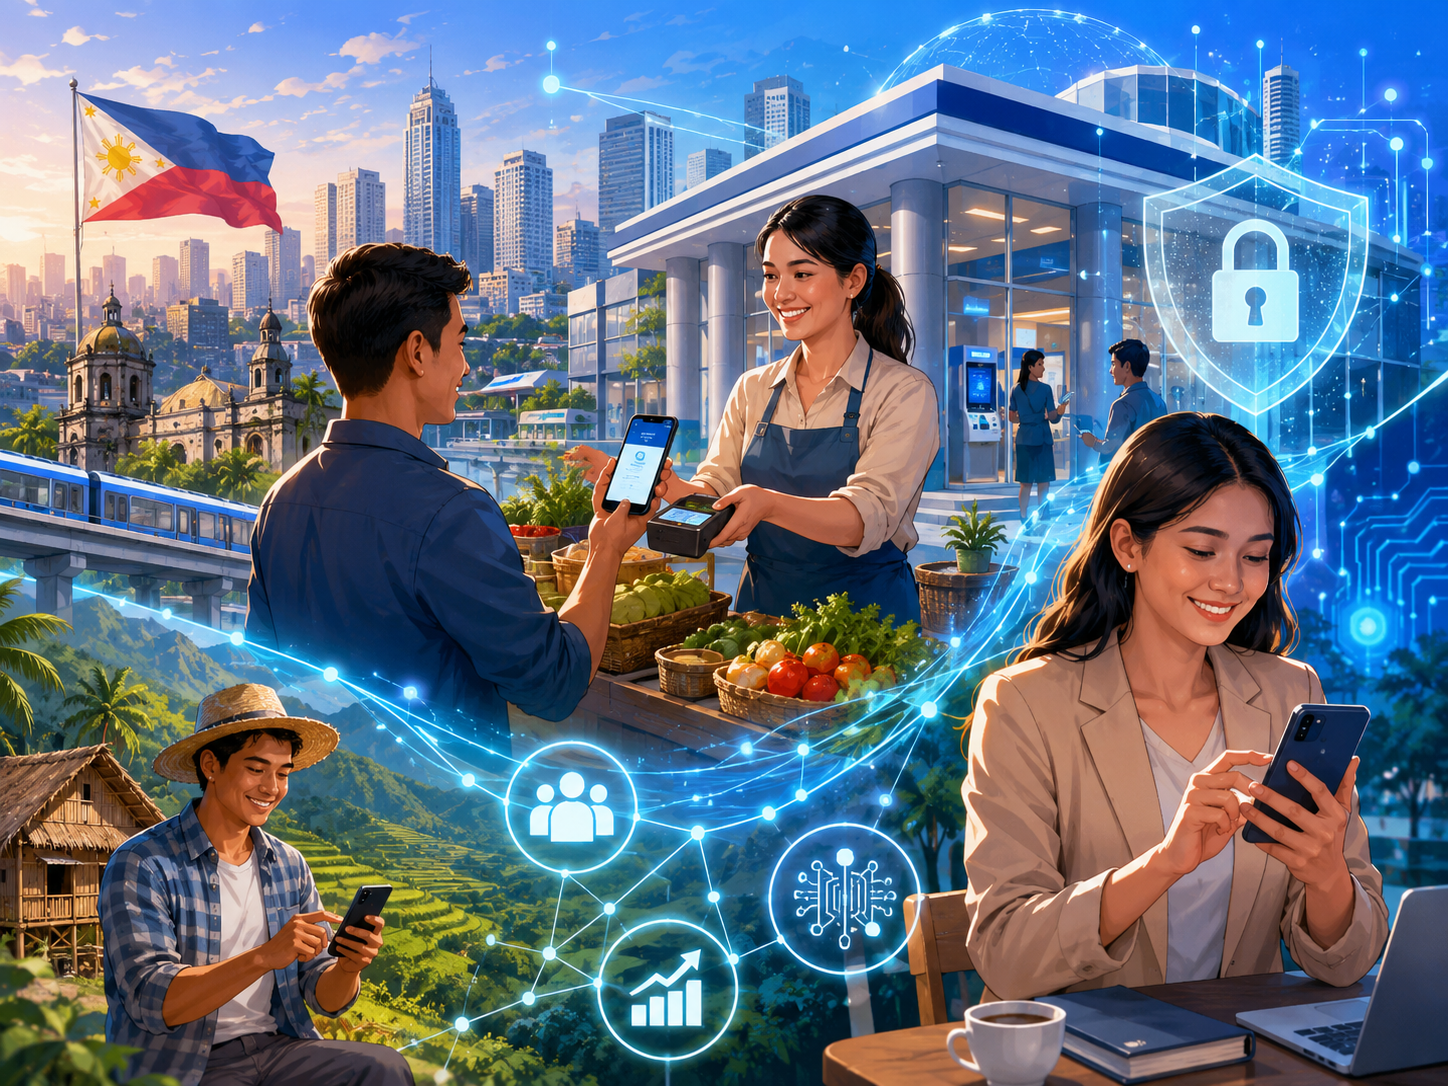
The Philippine banking sector’s deposit war is not only being fought in Makati boardrooms and Silicon Valley-funded app studios. It is also being fought in the provinces, among tricycle drivers, market vendors, and gig workers who until recently had no practical way to open a savings account at all. The BSP has long identified financial inclusion as a core mandate, and the growth of digital deposit products is, on paper, a direct contribution to that goal.
A March 2026 development illustrates how the inclusion story and the deposit competition story are converging. The Palawan Group of Companies, in partnership with Rizal Commercial Banking Corp. (RCBC), launched PalaSave, a digital savings feature embedded directly in the PalawanPay e-wallet . The product offers a 4 percent annual interest rate, zero maintaining balance, and a maximum balance of ₱50,000 — a structure explicitly designed for the unbanked and underbanked. Within its first months, PalaSave registered 60,000 accounts and accumulated approximately ₱50 million in deposits, with a target of one million users and ₱1 billion in savings within a year .
Inclusion Is Not the Same as Engagement
The PalaSave model is instructive precisely because it does not pretend to compete with Tonik’s 8 percent time deposit or Maya’s boosted rates. Its 4 percent rate is respectable but not spectacular. What makes it notable is the distribution channel: PalawanPay’s existing network of pawnshops and remittance centers, which reaches communities that have never had a bank branch within walking distance.
RCBC Executive Vice President Lito Villanueva described the target demographic as people who are “financially capable but systematically invisible” — undocumented gig workers, freelancers, and informal earners whose income is real but whose financial footprint is not . For these Filipinos, the barrier to saving was never a lack of discipline. It was a lack of access.
The Profitability Question Hanging Over Inclusion
There is a tension at the heart of the inclusion narrative, however. The BSP has noted that profitability remains a hurdle for most digital lenders . Serving low-balance, high-transaction-volume customers is expensive. The economics of a ₱500 savings account that generates ₱20 in annual interest income for the depositor — and far less in net revenue for the bank after operating costs — are challenging at best.
This is why the involvement of traditional institutions like RCBC matters. A standalone digital bank betting its entire business model on unbanked customers with small balances would struggle to survive. A large commercial bank using digital channels to extend its reach into underserved segments, while cross-selling other products over time, has a more viable path. The PalaSave partnership is, in essence, a bet that today’s unbanked tricycle driver with ₱2,000 in savings becomes tomorrow’s borrower, remittance customer, or micro-insurance policyholder.
What Young Filipinos Actually Need From Digital Banking
For the Gen Z segment specifically, the inclusion conversation often focuses on the wrong metric. The relevant question is not whether a young Filipino has a savings account. It is whether that account helps her build a financial cushion that can absorb a medical emergency, a job loss, or a typhoon. The BSP’s second-quarter 2026 data showing a collapse in saving intentions among low-income households — to -15.8 — suggests that access alone is not solving the resilience problem .
Digital banks have made it easier to open an account and to earn a rate that at least gestures toward beating inflation. They have not yet solved the harder problem of making it easier to leave money in that account when life demands otherwise.