The Unbanked Are Not Unscorable
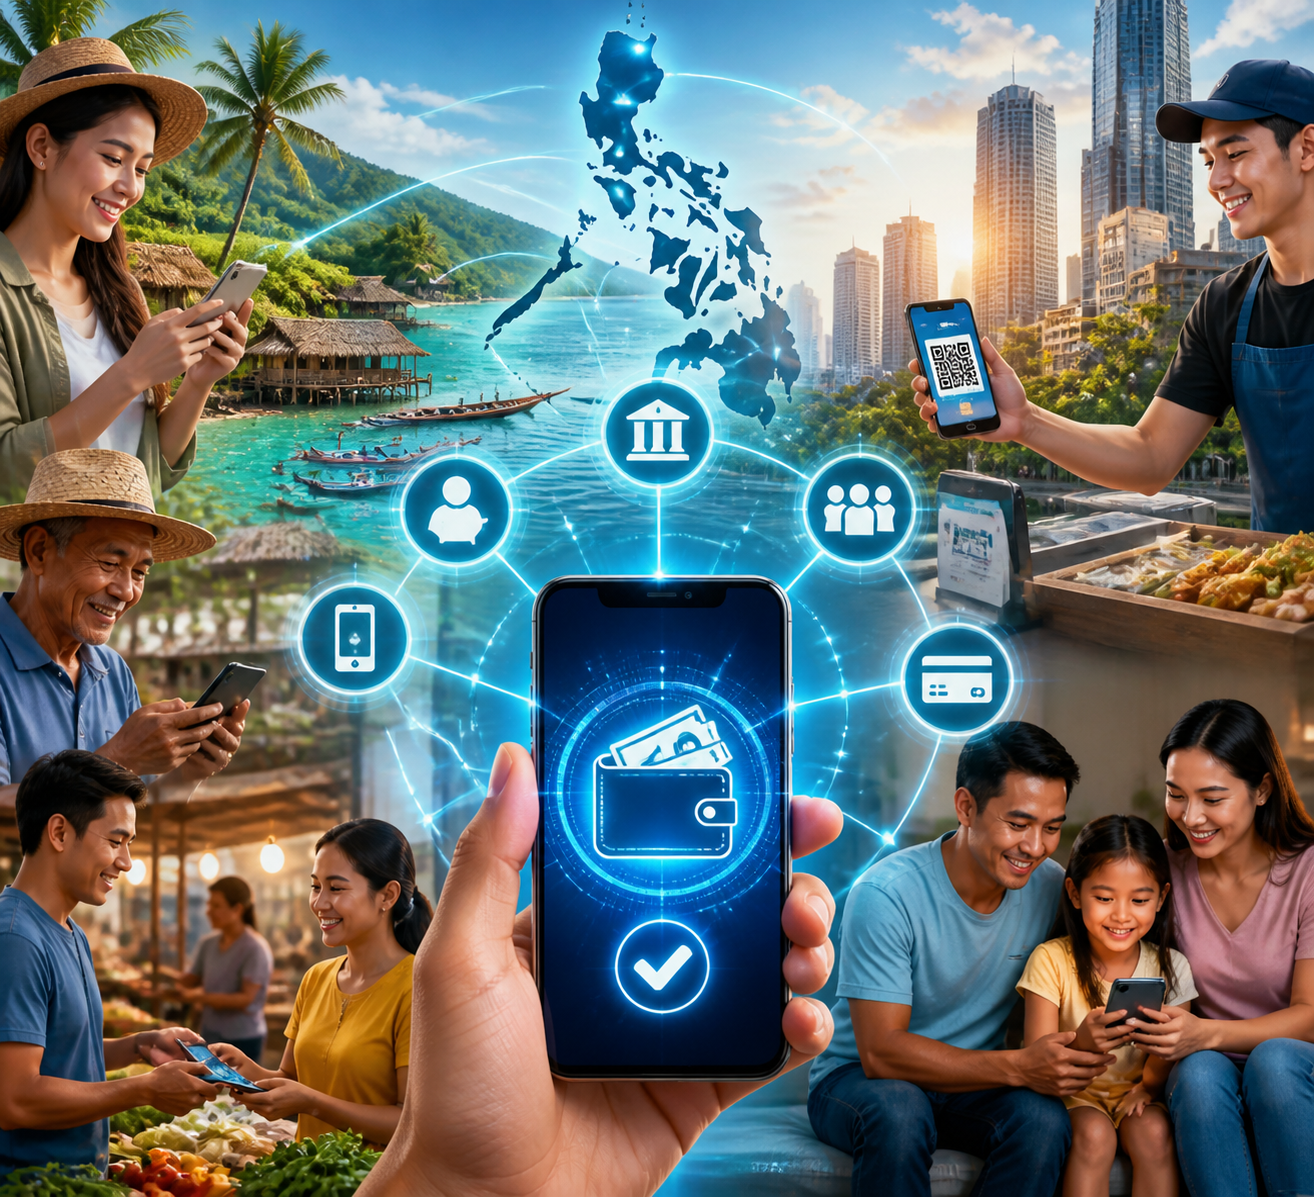
There is a persistent myth in traditional finance: if you don’t have a bank account, you don’t have a financial identity. Open Finance shatters this myth. In the Philippines, where a significant portion of the population relies on e-wallets and remittances, the data generated by these activities is a goldmine of creditworthiness indicators.
Alternative Credit Scoring: The Game Changer
The BSP’s Open Finance Framework explicitly supports the use of alternative data for credit assessment. Lenders are now integrating non-traditional data points—such as bill payment history, e-wallet transaction frequency, and remittance inflows—into their underwriting models.
Empowering the Micro-Entrepreneur
Consider the sari-sari store owner in Cebu. She has no formal credit history, but she has a GCash account with three years of consistent daily transactions. Under Open Finance, she can authorize a lender to view this data. The lender can then assess her cash flow reliability and offer a micro-loan at a fair rate, rather than the exorbitant rates of informal lenders.
The Rise of Micro-Insurance
Beyond lending, the framework is unlocking new frontiers in insurance. The BSP has expanded the scope of Open Finance beyond account information to include payments, lending, and insurance services. This allows insurers to design micro-policies tailored to the specific needs and risk profiles of underserved communities.
Real-Time Risk Assessment
With consent-driven access to transactional data, insurers can offer dynamic premiums. A tricycle driver with a consistent record of daily digital payments might qualify for a discounted accident insurance policy, as his regular income stream represents a lower risk profile.
The 2026 Horizon: A Fully Inclusive Ecosystem
The vision for 2026 is an ecosystem where a Filipino’s digital financial footprint is a passport to a full suite of services. The BSP is actively working with fintechs like Salmon and platforms like LenderLink to build the infrastructure for real-time credit data sharing based on Open Finance principles.
The transition from a bank-centric to a data-centric financial system is not just a technological upgrade; it is a profound shift toward economic democracy. The tools are in place. The regulatory will is evident. The only remaining variable is the speed of adoption.